



Key Benefits of Comparing Public Liability Insurance Rates for Australian Businesses
As an Australian business owner, you face numerous financial risks daily. Accidents can happen at any time, whether it's a slip and fall on your premises or damage caused by your products or services. These incidents can lead to costly legal actions that may put significant strain on your business finances. - read more

5 Tips for Reducing Your Liability Insurance Premiums in Australia
Liability insurance is a crucial form of protection that offers coverage against claims resulting from injuries and damage to people or property. Within the bustling landscape of Australian businesses, possessing this form of insurance is key to financial security and continuity. It acts as a safety net, ensuring businesses can manage risks without bearing the full brunt of potentially costly legal claims. - read more

Proven Strategies for Slashing Your Business Liability Insurance Costs
Welcome to our comprehensive guide on public liability insurance, an essential safeguard for businesses across Australia. Navigating the complexities of liability insurance can be a daunting task for many business owners, but it’s a critical component of your business protection plan. If incidents such as accidents or property damage occur, liability insurance is the barrier that stands between your business and financial calamity. - read more

Common Myths About Public Liability Insurance Debunked
Today, we're diving into the world of public liability insurance, a crucial topic for anyone running a small business or working as a self-employed professional in Australia. - read more
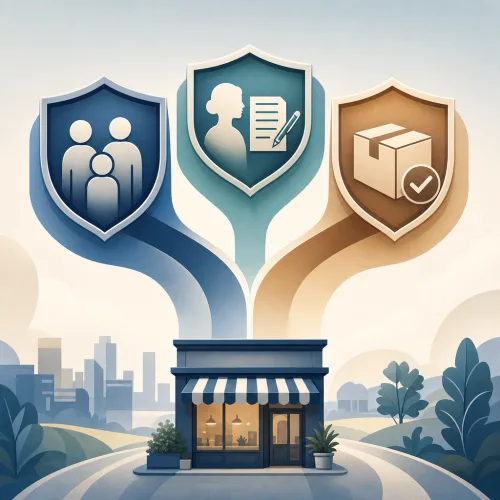
Types of Liability Insurance in Australia: Public Liability, Professional Indemnity and Product Liability Explained
Liability insurance can cover different business risks depending on whether a claim involves third-party injury, property damage, professional advice or products supplied. This guide explains the main types of liability insurance in Australia and how they differ. - read more

No comments yet. Be the first to share your thoughts.