The information on this website is general in nature and does not take into account your objectives, financial situation, or needs. Consider seeking personal advice from a licensed adviser before acting on any information.
Public liability and professional indemnity insurance protect Australian businesses against different types of risk. Public liability focuses on third-party injury or property damage connected with business activities, while professional indemnity focuses on claims arising from professional advice or services.
Public liability and professional indemnity insurance: why the distinction matters
Australian businesses can face very different types of claims depending on how they operate, who they deal with and what they provide. Two common forms of business insurance are public liability insurance and professional indemnity insurance, but they are designed for different exposures.
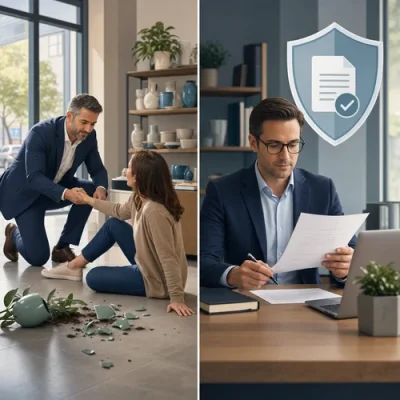
Public liability insurance is generally concerned with injury to third parties or damage to third-party property arising from business operations. Professional indemnity insurance is generally concerned with allegations that professional advice or services caused a client financial loss, harm or other adverse consequences.
Understanding the difference can help business owners and professionals ask better questions when reviewing their risk profile, policy wording, exclusions and claims process. This article is educational in nature and does not replace advice based on your business circumstances.
Quick comparison: public liability vs professional indemnity
| Feature |
Public liability insurance |
Professional indemnity insurance |
| Main purpose |
Responds to claims involving third-party personal injury or property damage connected with business activities. |
Responds to claims involving professional negligence, errors, omissions or breach of duty in advice or services. |
| Typical trigger |
A member of the public, customer, client, supplier or other third party is injured, or their property is damaged. |
A client alleges that professional work, advice, design, calculation, implementation or service caused loss. |
| Common examples |
A customer slips in a shop, business equipment damages a passer-by's property, or work at a client site damages property. |
An accountant makes a miscalculation, an IT consultant's implementation causes disruption, or a design professional is accused of faulty work. |
| Nature of loss |
Physical injury or physical property damage. |
Financial loss or other consequences arising from professional services or advice. |
| Who may consider it |
Businesses with public interaction, premises, site work, client visits or activities that could affect third-party property. |
Professionals and businesses that provide expertise, advice, consulting, designs, recommendations or specialist services. |
What is public liability insurance?
Public liability insurance is designed to protect a business against claims made by third parties for personal injury or property damage arising from the business's operations. It can help with compensation payments and legal expenses where the policy responds to the claim.
Typical public liability scenarios include:
- a customer slipping on a wet floor at a retail premises;
- equipment or materials from a worksite damaging a passer-by's property;
- business activity at a client location causing damage to the client's property; and
- injury connected with products manufactured or supplied by the business, depending on the policy wording.
Public liability insurance is often relevant for businesses that interact with customers, suppliers, visitors or the general public. This can include retail stores, restaurants, trades, construction sites, venues and businesses that visit client premises.
For a more detailed explanation of this cover type, see this guide to public liability insurance in Australia.
What is professional indemnity insurance?
Professional indemnity insurance, sometimes referred to as professional liability insurance, is designed for professionals and businesses that provide advice or services. It can respond to claims alleging negligence, errors, omissions or breach of duty in professional work.
The focus is not usually a slip, fall or damaged item of property. Instead, the issue is whether the professional service or advice allegedly caused a client loss. Examples from the source article include:
- an accountant facing a claim after a miscalculation that contributes to a client's financial loss;
- an IT consultant whose software implementation causes downtime and loss for a client's business;
- an engineer facing allegations connected with faults in a designed structure; and
- professionals such as consultants, architects, financial advisers, designers or medical service providers facing claims linked to the expertise they provide.
Professional indemnity insurance can help with legal defence costs and compensation where the claim falls within the policy. As with any insurance product, the actual response depends on the policy terms, limits, conditions and exclusions.
The key difference: physical incidents versus professional services
The simplest way to separate the two policies is to look at what caused the claim.
- Public liability: the claim usually arises from business operations causing third-party injury or property damage.
- Professional indemnity: the claim usually arises from advice, recommendations, designs, calculations, consulting or services that are alleged to be negligent or deficient.
For example, if a visitor trips over an obstacle in your premises and is injured, that points towards public liability. If a client alleges that your professional advice caused them financial loss, that points towards professional indemnity.
A common misconception is that public liability insurance covers mistakes in professional advice. The source article makes clear that these are different risks. A business may need one, both or neither depending on its activities, contractual requirements and risk exposure.
How to decide which cover may be relevant
Start by analysing the business activities that create risk. Useful questions include:
- Do customers, visitors, suppliers or members of the public come to your premises?
- Do you work at client premises, public sites or shared locations?
- Could your work damage third-party property or create a physical injury risk?
- Do you provide advice, designs, professional opinions, reports, calculations or recommendations?
- Could a mistake, omission or implementation issue in your services cause a client financial loss?
- Do your contracts require a certificate of insurance or specify particular cover types?
A retail store or restaurant with public foot traffic may give priority to public liability. A consultancy, design practice, accounting business or advisory firm may need to pay close attention to professional indemnity. Some businesses sit in both categories.
For example, a fitness trainer may interact closely with the public while also providing guidance. A technology consultant may visit client sites and provide professional implementation services. In these situations, the source article notes that a combined approach may be worth considering, subject to the policy terms and the actual risks involved.
When a combined insurance approach may be considered
Some businesses have both physical interaction risk and professional service risk. In those cases, holding only one type of policy may leave an important exposure unaddressed.
A combined insurance arrangement may be relevant where business operations include both:
- direct interaction with clients, customers, suppliers or the public; and
- professional advice, recommendations, designs, consulting, implementation or specialist services.
The important point is not simply whether the policies are bundled together administratively. It is whether the wording, limits, exclusions and claims conditions actually respond to the risks the business faces. Policy documents should be checked carefully for gaps, overlaps and conditions.
Arranging and reviewing cover
The source article sets out a practical sequence for arranging public liability or professional indemnity insurance:
- Identify the business's specific risks and the level of cover being considered.
- Research insurers, policy features and coverage options.
- Seek assistance from an insurance broker or other insurance professional where the risks are complex.
- Review the policy terms, including inclusions, exclusions, limits and claim conditions.
- Clarify uncertainties before finalising the policy.
- Provide required documentation and pay the premium if proceeding with the cover.
When you are researching providers, it may be useful to compare business insurance quotes alongside the policy wording rather than focusing only on the premium.
Because cover needs can change, insurance should not be treated as a one-time task. Annual reviews before renewal can help identify changes in business size, services, client types, locations, contractual requirements or public exposure. A Public Liability Insurance Calculator may also help frame questions about potential cover levels when discussing options, although the policy decision still depends on your circumstances and policy terms.
Where the business risk profile is not straightforward, insurance brokers may be able to help interpret cover options and explain policy differences.
Policy exclusions and coverage gaps
Exclusions are specific circumstances, conditions or types of loss that a policy does not cover. They matter because two policies with similar names may respond differently in practice.
When reviewing public liability or professional indemnity insurance, consider:
- what activities are included or excluded;
- whether work at client sites is covered;
- whether particular services, advice areas or industries are excluded;
- what limits and sub-limits apply;
- what documents or notifications are required when a claim or potential claim arises; and
- whether the business has changed since the policy was first arranged.
If a gap is identified, the source article suggests discussing it with the insurer or broker. Options may include changing the policy, adding additional cover or seeking a specialist insurer for unusual risks.
Claims process: what to expect
The claims process differs by insurer and policy, but the source article identifies several common steps for both public liability and professional indemnity claims.
Public liability claims
If an incident occurs that may lead to a public liability claim, the business should notify the insurer promptly. The insurer may require a claim form, details of the incident and supporting evidence such as photographs, witness statements or other records.
The insurer will then assess whether the claim falls within the policy. This may involve investigating the circumstances, reviewing documentation and managing negotiations or legal issues where the policy responds.
Professional indemnity claims
A professional indemnity claim often begins with an allegation about advice or services. The business should notify the insurer promptly and provide relevant documents, such as contracts, correspondence, reports, project files and records of the work performed.
The source article also notes that it is important not to acknowledge liability or make offers to the complainant without the insurer's guidance. If the policy responds, the insurer may manage the legal defence and any settlement process or court outcome.
Records that can support a claim
Good record-keeping can make the claims process easier to navigate. Useful records may include:
- contracts and scopes of work;
- emails, letters and client instructions;
- incident reports and photographs;
- witness details;
- reports, advice documents and deliverables;
- policy documents and renewal records; and
- communications with the insurer or broker.
For a broader overview of claim steps and documentation, see this guide to the insurance claims process.
Common misconceptions
- "Public liability covers advice mistakes." Public liability is generally aimed at third-party injury or property damage, not professional advice errors.
- "Professional indemnity covers all business incidents." Professional indemnity is generally concerned with professional services and advice, not every operational risk.
- "One policy is always enough." Some businesses may need only one type of cover, while others may need both. The answer depends on the actual business activities and policy terms.
- "The policy name tells the whole story." The wording, exclusions, limits and claims conditions determine how cover may respond.
Final thoughts
Public liability and professional indemnity insurance address different parts of business risk. Public liability focuses on third-party injury and property damage arising from business activities. Professional indemnity focuses on allegations connected with professional advice, services, errors or omissions.
For many Australian businesses, the practical task is to map the policy type to the risk. Review what the business does, who it interacts with, where work is performed and what could go wrong. Then check whether the policy wording, limits and exclusions align with those risks. Where the answer is unclear, professional guidance can help clarify the options.
Published: Thursday, 28th Mar 2024
Author: Paige Estritori





No comments yet. Be the first to share your thoughts.